Andrew Ross Sorkin
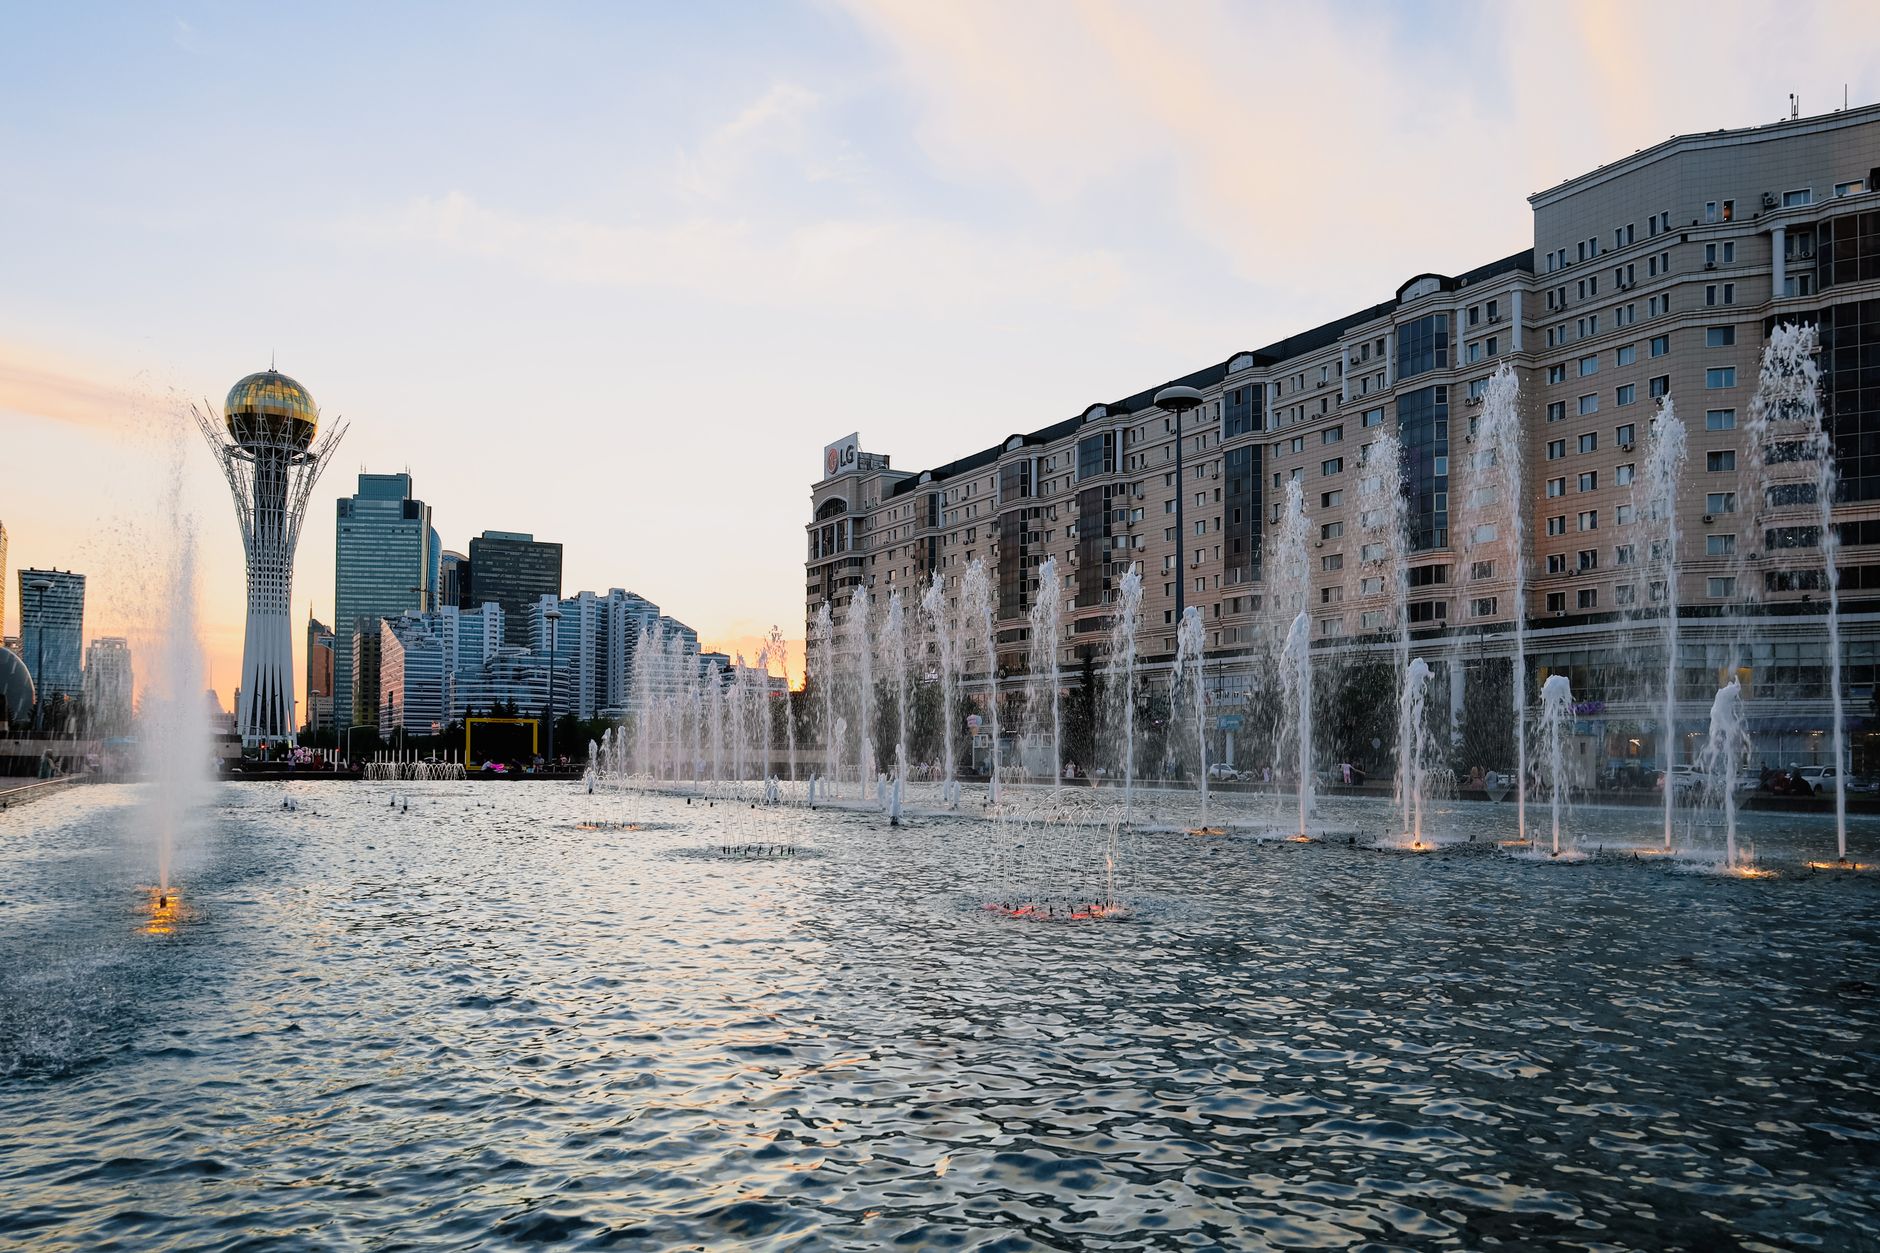
CodeCoin has advanced its push into regulated digital payments by securing a Kazakhstan authorization covering fiat-stablecoin issuance and entering a cooperation agreement with Altyn Bank, positioning the company to develop cross-border payment services at the intersection of blockchain infrastructure and conventional banking. The announcements were made around Astana Finance Days 2026, where financial institutions, regulators and technology companies gathered to discuss regional capital markets, tokenization and digital-finance infrastructure.
The Hong Kong-based payment technology company said on September 15 that the Astana Financial Services Authority, or AFSA, had approved its stablecoin issuance license. CodeCoin also signed a memorandum of understanding with Altyn Bank during the conference, with representatives of institutions including Mastercard, Citi and China International Capital Corporation present at the signing, according to the company’s announcement.
The regulatory status requires an important distinction. AFSA’s public register lists CodeCoin Tech Ltd. as a FinTech Lab participant under license number AFSA-A-LA-2026-0025, with the authorization effective from September 7. The permitted activity is described as providing money services relating to digital assets as the issuer of a fiat stablecoin. However, AFSA currently lists the status as pending approval and states that the license has been granted while approval for commencement of operations remains outstanding.
That means CodeCoin has moved beyond the preliminary stage of its Kazakhstan licensing process, but the register does not yet indicate unrestricted operational commencement. The distinction matters for customers and counterparties assessing the maturity of new stablecoin projects. Regulatory authorization can establish the legal perimeter for a product, while separate operational conditions may still need to be satisfied before services are commercially offered under that authorization.
CodeCoin had announced in April that it received preliminary approval relating to stablecoin issuance in Kazakhstan and was awaiting further AFSA authorization. The September development therefore represents a material progression in a licensing process that has been underway for several months. The company has framed Kazakhstan as a strategic entry point into Central Asian and Eurasian payment corridors, where trade flows increasingly connect China, Central Asia, Europe and other international markets.
The partnership with Altyn Bank provides the second component of that strategy. CodeCoin said the memorandum is intended to explore cooperation in fintech, digital finance, cross-border payments and related applications using the bank’s local financial infrastructure. Altyn Bank is a subsidiary of China CITIC Bank Corporation Limited, giving the arrangement an additional connection to established banking networks serving trade and corporate customers.
The Astana International Financial Centre independently confirmed that CodeCoin Tech Ltd. and Altyn Bank JSC were among the organizations signing memoranda during Astana Finance Days. AIFC said the cooperation covers cross-border financial services, fintech, asset management, trade finance and payment infrastructure. It also listed a separate memorandum between CodeCoin and Delta DA Ltd. among agreements concluded around the event.
For CodeCoin, the combination of regulatory status and a banking relationship could be more consequential than either development on its own. Stablecoin companies seeking enterprise adoption need more than blockchain issuance technology. They typically require mechanisms for fiat funding and redemption, customer verification, transaction monitoring, liquidity management, bank settlement and connections to existing payment systems. A local banking partner can potentially provide part of that bridge between tokenized value and traditional accounts.
CodeCoin is targeting the persistent frictions associated with cross-border commercial payments. International businesses can face multiple intermediaries, limited banking hours, slow settlement cycles and incomplete visibility into payment status. These problems become more significant for companies managing suppliers, merchants and treasury operations across several currencies and jurisdictions. CodeCoin argues that regulated digital assets can shorten parts of the settlement process while producing clearer transaction records.

The company says its infrastructure is aimed at corporate payments, merchant transactions, international remittances and multi-currency fund movements. Rather than positioning stablecoins primarily as speculative assets, CodeCoin is emphasizing their potential role as settlement instruments embedded within payment workflows. That approach mirrors a broader shift across financial technology, where stablecoin developers increasingly focus on business-to-business settlement, treasury operations and international commerce.
The commercial proposition is particularly relevant in markets where correspondent banking chains can make smaller cross-border transactions disproportionately expensive. A payment may move through several banks before reaching the recipient, creating fees, reconciliation work and uncertainty over timing. Stablecoin-based systems seek to reduce some of those steps by moving tokenized value across blockchain networks while retaining regulated gateways for entry into and exit from national currencies.
Yet the technology does not eliminate the need for financial regulation. Stablecoin systems still need mechanisms for reserve management, customer due diligence, anti-money-laundering controls, sanctions screening and transaction monitoring. Companies must also determine how redemption rights, client assets and operational risks are handled. CodeCoin says risk management, fund security and transaction traceability are central to its product architecture and that it incorporates compliance controls and anti-money-laundering frameworks into its operations.
The AFSA authorization places those ambitions inside Kazakhstan’s regulated digital-asset framework. The AIFC has sought to position itself as a financial hub connecting Central Asia with international capital and financial technology. Its framework includes digital-asset service providers and a FinTech Lab through which companies can test financial products within defined regulatory parameters. CodeCoin’s current registration falls within that FinTech Lab structure rather than representing evidence of an unrestricted global stablecoin authorization.
Kazakhstan also offers geographic relevance for CodeCoin’s cross-border strategy. The country lies along major trade routes between China, Central Asia, Russia and Europe and has sought to expand its role in regional logistics, financial services and technology. CodeCoin has already pursued partnerships in the country. In June, the company announced a memorandum with the Alatau City Authority State Fund aimed at developing cross-border digital-payment infrastructure connecting the Guangdong-Hong Kong-Macao Greater Bay Area with Central Asia.
The latest announcements therefore suggest that CodeCoin is attempting to construct a payment corridor through several layers: regulatory licensing, local banking relationships and institutional partnerships. If that structure progresses to commercial operation, it could allow businesses to initiate transactions through conventional financial interfaces while using digital-asset infrastructure for portions of settlement or value transfer.
Such hybrid architectures have become increasingly significant as banks and fintech companies reassess stablecoins. Early cryptocurrency payment models frequently sought to bypass established financial intermediaries. The newer institutional approach is more collaborative. Banks can provide regulated fiat access, account infrastructure and compliance capabilities, while blockchain networks can potentially provide faster or more programmable settlement across jurisdictions.
CodeCoin is also considering longer-term payment applications involving artificial-intelligence agents. The company has argued that autonomous software capable of ordering services or initiating commercial transactions will require controlled payment permissions, identity frameworks, spending limits and auditable transaction histories. Under such a model, companies could authorize software agents to execute payments only within predetermined counterparties, amounts and time periods.
That concept remains an emerging area of fintech infrastructure, but it illustrates the broader architecture CodeCoin is pursuing. Rather than offering only a stablecoin, the company is presenting itself as a multi-currency payment infrastructure provider that combines bank rails, digital assets and programmable financial controls. The commercial viability of that model will depend on whether the company can translate regulatory permissions into usable products and obtain sufficient banking, liquidity and corporate-client connectivity.

CodeCoin has also highlighted security as a prerequisite for institutional adoption. The company says its information-security management system received ISO/IEC 27001 certification in April. It has described fund segregation, auditable payment processes and traceable transaction records as parts of its operating framework. Those features are especially relevant for corporate treasury teams, which generally require controls and reconciliation standards closer to banking infrastructure than consumer cryptocurrency applications.
The Altyn Bank agreement does not by itself establish that specific commercial products or payment corridors are already live. Memoranda of understanding generally provide frameworks for cooperation rather than binding commitments to deploy a defined service. The next significant indicators will therefore include details on product launches, supported currencies, stablecoin reserve arrangements, redemption mechanics, participating corporate clients and the completion of AFSA requirements for commencement of operations.
Market participants will also watch how CodeCoin structures the relationship between its fiat stablecoin activities and existing banking infrastructure. One of the central operational questions facing stablecoin payment providers is how seamlessly businesses can move between bank deposits and tokenized balances. Reliable minting and redemption processes, transparent settlement rules and adequate liquidity are critical if stablecoins are to function as working-capital tools rather than assets that require separate crypto-market management.
Another issue is interoperability. Corporate clients rarely operate on a single blockchain or banking system. Payment providers serving international trade need to support multiple currencies, compliance regimes and settlement destinations while maintaining consistent transaction records. CodeCoin says its strategy is to reduce foreign-exchange and intermediary friction through flexible payment routes and multi-currency infrastructure, although the scale and economics of those services will become clearer only after operational rollout.
The timing of the agreement also reflects Kazakhstan’s effort to deepen its financial links with regional and international institutions. Astana Finance Days 2026 brought together thousands of participants from dozens of countries and produced agreements spanning regulatory cooperation, capital markets, sustainable finance and fintech. AIFC described the event as a venue for translating regulatory and investment discussions into financial instruments and commercial agreements across Kazakhstan and the broader region.
For the stablecoin sector, CodeCoin’s move reinforces a broader transition from experimentation toward regulated financial integration. The competitive advantage for payment-focused stablecoins is increasingly likely to depend not merely on blockchain speed but on access to banks, regulatory clarity, reserve transparency, compliance technology and distribution through actual commercial networks.
CodeCoin’s Kazakhstan authorization and Altyn Bank memorandum give it additional pieces of that infrastructure, but execution remains the central question. The AFSA register’s pending-commencement status means the company still has a regulatory milestone to clear before the authorization can be treated as fully operational. After that, investors, customers and industry observers will be able to assess whether the company can convert its licenses and institutional partnerships into measurable payment volume and sustainable enterprise adoption.
If it succeeds, Kazakhstan could become a practical testing ground for a model increasingly important across global fintech: regulated stablecoin settlement operating alongside, rather than outside, the banking system. For CodeCoin, the immediate significance of the September announcements is therefore less about launching another digital token and more about assembling the legal and institutional infrastructure required to move digital money through real-world commercial payment channels.